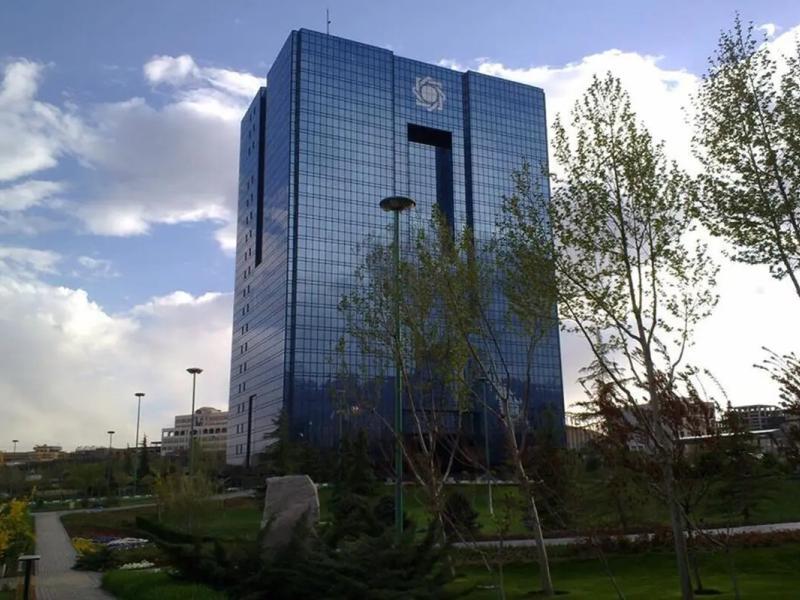
Iran’s Central Bank has rolled out six measures to ease foreign trade, with early results already visible. Mehdi Darabi, the bank’s forex assistant, said reforms launched in January have accelerated the return of export earnings, created an excess supply of foreign currency in the bank’s systems, and cut red tape for importers.
A change allows exporters to repatriate earnings in cash. Previously barred, this route alone brought back more than $1.5 billion within the first months. Under Article 11 of the Seventh Development Plan, importers and exporters can trade directly. Daily forex deals between them have jumped from under $1 million to over $50 million, letting importers secure hard currency for raw materials and production goods within a day—no allocation queue.
The bank now acts as intermediary: exporters sell forex to banks, which must sell it to importers under Central Bank supervision. Cash can likewise be sold to banks for import use. Darabi said corrective regulations are moving through the government’s Economic Committee with ministries and the private sector, aiming to streamline both imports and exports. The package marks a significant shift in Iran’s trade policy. It aims to reduce delays and boost transparency.